
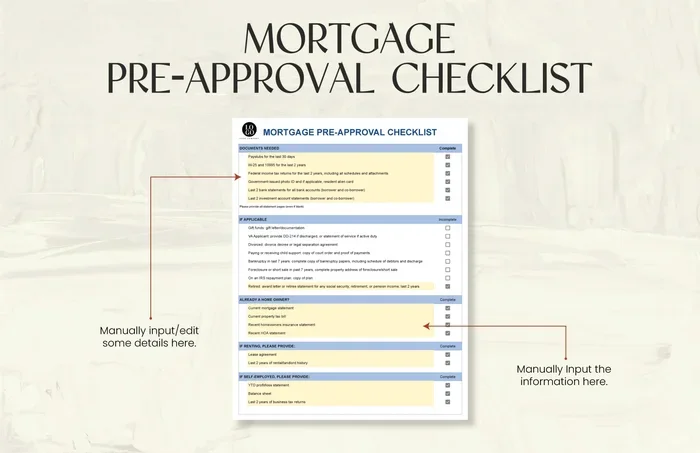
Does getting pre approved for a mortgage affect your credit? Yes, it triggers a hard inquiry that may drop your score slightly. The impact is usually small and temporary. Smart shopping within a short window keeps damage minimal.
This is a comprehensive guide about Does Getting Pre Approved For A Mortgage Affect Your Credit.
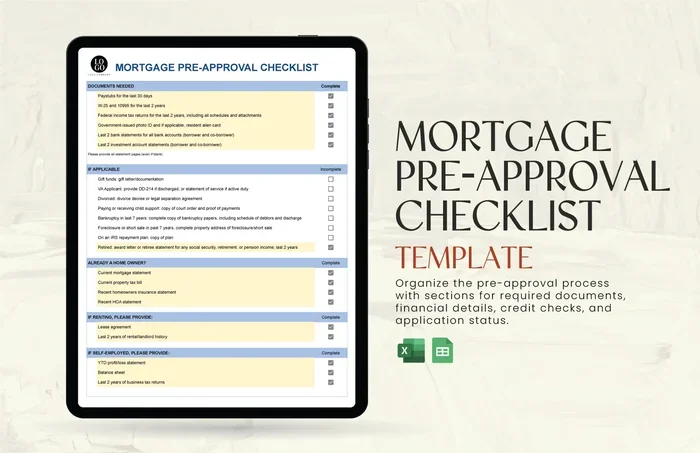
Visual guide about mortgage pre approval credit check
Image source: images.template.net
Visual guide about mortgage pre approval credit check
Image source: images.template.net
Visual guide about mortgage pre approval credit check
Image source: img.paperform.co
Key Takeaways
- Hard inquiry impact: A mortgage pre approval places a hard pull on your credit report, typically lowering your score by a few points.
- Short shopping window: Multiple lender checks within a focused period usually count as one inquiry for scoring purposes.
- Temporary effect: The score dip is brief and often recovers within a few months as you continue good credit habits.
- Pre qualification differs: A soft pull pre qualification does not affect your score, while a full pre approval usually does.
- Timing matters: Apply when your credit profile is stable, and avoid new debt right before or during the process.
- Rate shopping helps: Comparing offers from several lenders can secure better terms with minimal credit impact.
- Monitoring helps: Check your reports for accuracy and dispute errors to keep your score as strong as possible.
[FEATURED_IMAGE_PLACEHOLDER]
Does Getting Pre Approved for a Mortgage Affect Your Credit
You are ready to buy a home. You want a clear budget. You also want to protect your credit score. So you ask a simple question. Does getting pre approved for a mortgage affect your credit? The short answer is yes, but the effect is usually small. A lender will check your credit file before giving you a pre approval letter. That check is called a hard inquiry. It can shave a few points off your score. The good news is that the dip is brief. It also fades fast when you keep paying bills on time.
Many buyers worry about this step. They fear one inquiry will ruin their score. That fear is understandable. But the reality is calmer. One hard pull is not a crisis. Even a few pulls in a short span are manageable. The key is to understand how the process works. Then you can plan it wisely. You can compare lenders. You can time your applications. You can keep your score healthy while you shop for the best deal.
In this guide, we will walk through the basics. We will explain hard pulls and soft pulls. We will talk about rate shopping windows. We will share simple tips to limit any drop. We will also answer common questions. By the end, you will know exactly what to expect. You will feel ready to move forward with confidence.
How a Mortgage Pre Approval Works
A pre approval is more than a quick guess. It is a lender review of your finances. The lender looks at your income. They check your debts. They review your credit file. They want to see if you can handle a home loan. If you pass the review, they give you a pre approval letter. This letter shows sellers that you are serious. It also helps you understand your price range.
The process starts when you submit an application. You share basic details. You give permission to check your credit. The lender then requests your report from one or more bureaus. This request is a hard inquiry. It becomes part of your credit history for a while. The lender also reviews your debt to income ratio. They look at your employment history. They check for recent late payments or high balances. All of this helps them decide your loan amount and likely rate.
It helps to know the difference between pre qualification and pre approval. Pre qualification is often lighter. It may use a soft pull or just self reported info. It gives a rough estimate. Pre approval is deeper. It usually requires a hard pull. It carries more weight with sellers. That is why buyers often choose pre approval before making an offer.
Soft Pulls and Hard Pulls Explained
Not every credit check is the same. A soft pull is gentle. It happens when you check your own score. It also happens during some background checks. A soft pull does not change your score. A hard pull is different. It happens when a lender reviews your file for a lending decision. A hard pull can lower your score by a small amount. The drop is usually a few points. Sometimes it is none at all. The exact impact depends on your overall file.
Hard inquiries stay on your report for two years. Their effect on your score fades over time. Most scoring models care more about recent activity. That means a single hard pull is a small event. It matters, but it is not a major setback. If you have a strong credit history, the dip is even less noticeable. If your file is thin, the impact may be a bit larger. Either way, it is temporary.
Does Getting Pre Approved for a Mortgage Affect Your Credit Score
This is the core question. Does getting pre approved for a mortgage affect your credit score? Yes, because the lender performs a hard inquiry. The size of the effect varies. For many people, the drop is minor. It might be one to five points. For some, it could be slightly more. The reason is simple. Scoring models view new credit activity as a possible risk signal. They want to see whether you are taking on a lot of new debt. A mortgage inquiry suggests you are seeking a large loan. So the model adjusts your score a bit.
The context matters too. If you have many recent hard pulls from different types of credit, the effect can stack. If your report is clean and stable, the effect is smaller. Your overall payment history still carries the most weight. So one mortgage inquiry will not undo years of good habits. It is a small blip, not a major shift.
What Factors Matter Most
Credit scores are built from several pieces. Payment history is the biggest piece. Amounts owed comes next. Length of credit history matters as well. New credit and credit mix also play a role. A hard inquiry falls under new credit. It is only one small part of the puzzle. That is why the impact stays limited. Your day to day habits matter far more. Paying on time helps your score. Keeping balances low helps too. Avoiding unnecessary new accounts helps as well.
If you are planning to apply, look at the whole picture. Check your current score. Review your report for errors. Pay down high card balances if you can. Do not open new cards right before you apply. These steps keep your score steady. They also make the small inquiry impact less noticeable.
Rate Shopping and the Credit Inquiry Window
Buying a home means comparing offers. You want a fair rate. You want solid terms. That means talking to more than one lender. The good news is that credit models understand this. They know shoppers compare rates. So they treat multiple mortgage inquiries in a short window as one event for scoring purposes. This is called rate shopping. It protects your score while you look for the best deal.
The exact window can vary by model. Some models use a tight window. Others use a longer one. In many cases, inquiries within a focused period are grouped together. That means you can check with several lenders without taking many hits. The key is to keep the process moving in a short time. Try to complete your comparisons within a few weeks. That keeps everything clustered. It also helps you move faster once you find the right loan.
How to Compare Lenders Smartly
Start by gathering a few options. Look at banks, credit unions, and online lenders. Ask about rates, fees, and closing costs. Request a pre approval from each one you seriously consider. Keep your applications close together. Avoid spreading them out over many months. That keeps the inquiries grouped. It also keeps your search efficient.
You can also ask lenders what they need. Some may want tax returns. Others may want pay stubs. Having your documents ready speeds things up. It also reduces back and forth. A smooth process means less stress. It also means less time waiting. That helps you stay within the shopping window.
Here is a simple comparison checklist you can use:
- Interest rate: Compare the base rate and the annual percentage rate.
- Points and fees: Ask about origination fees, application fees, and discount points.
- Closing costs: Review estimated closing costs and which fees are fixed.
- Rate lock terms: Check how long the rate lock lasts and whether it costs extra.
- Customer service: Note how quickly each lender responds and explains details.
How Long the Impact Lasts
People often ask how long the dip lasts. The honest answer is that it depends. For most buyers, the effect is short lived. Your score may bounce back within a few months. The inquiry itself remains on your report for two years. But its influence on your score fades much sooner. After the first few months, it matters less and less.
Your actions after the inquiry matter a lot. Keep paying every bill on time. Keep card balances low. Do not open new credit lines unless you need them. These habits help your score recover. They also help it grow over time. If you avoid new debt during your home search, your file stays stable. That stability is exactly what scoring models like to see.
What If Your Score Drops More Than Expected
Sometimes the drop feels larger than you expected. That can happen if your file is thin. It can also happen if you had other recent inquiries. If that occurs, do not panic. Check your report for accuracy. Make sure the inquiry is correct. If you see an error, dispute it. Then focus on steady habits. Time and consistency do the rest.
If you are concerned, you can ask a lender how the inquiry may affect your loan terms. In many cases, the small dip does not change your approval or your rate. Lenders look at the full picture. They care about your income, your debts, and your payment history. One small score change rarely changes the outcome.
Tips to Protect Your Credit During the Process
You can take simple steps to protect your score. These steps are easy to follow. They also help your loan application look strong. The goal is to keep your file stable. You want no surprises when the lender reviews your credit.
First, check your reports before you apply. Look for mistakes. Dispute anything that looks wrong. Accurate reports help your score. They also prevent delays. Second, pay down high card balances. Lower utilization helps your score. It also improves your debt to income picture. Third, avoid new credit cards or loans. Every new account adds a hard pull. It also lowers your average account age. Skip both if you can.
A Few Smart Habits
Keep your applications close together. Use the rate shopping window to your advantage. Have your documents ready. This keeps the process fast. Fast is good because it keeps inquiries clustered. It also shows lenders you are organized. Stay calm and steady. Do not make big financial changes during the search. Do not quit a job if you can avoid it. Do not make large purchases on credit. Keep things quiet and consistent.
If you want extra peace of mind, monitor your score during the process. Use a free tool or a bank feature. Watch for changes. If you see a dip, remember that it is usually temporary. Keep doing the right things. Your score will settle. You will be ready when you find the right home.
Quick tips to remember:
- Gather documents early: Pay stubs, tax returns, and bank statements save time.
- Limit new debt: Hold off on car loans or new cards until after closing.
- Keep balances low: Lower card utilization supports a stronger score.
- Use one window: Complete your lender comparisons in a short span.
- Verify reports: Check for errors and fix them before you apply.
Common Mistakes to Avoid
Some buyers make simple mistakes that create needless stress. One common mistake is waiting too long between lenders. That spreads out inquiries. It also slows your search. Another mistake is opening new credit right before closing. That can change your debt picture. It can also trigger another hard pull. Both are avoidable.
Another mistake is ignoring your credit report. If there is an error, it may drag your score down for no reason. Fix it early. Another mistake is chasing a perfect score. You do not need perfection. You need a solid, stable profile. Focus on the basics. Pay on time. Keep balances reasonable. Compare lenders wisely. That is enough for most buyers.
Expert Insight
Loan officers often say the same thing. They want a clear, stable file. They do not expect a flawless score. They care more about consistency. A small inquiry is normal. It is part of the process. What matters is that you are honest, prepared, and steady. If you follow that approach, the credit impact stays small. The process also feels much easier.
Conclusion
So, does getting pre approved for a mortgage affect your credit? Yes, it creates a hard inquiry. The effect is usually small. It is also temporary. You can limit the impact by shopping in a short window. You can protect your score by paying bills on time and keeping balances low. You can avoid new debt while you search. These simple steps keep your file strong. They also help you find the best loan for your budget.
Home buying is a big step. A pre approval helps you move with clarity. It shows sellers you are ready. It also helps you shop with confidence. Understand the process. Plan it well. Then you can focus on the fun part, which is finding the right home. With a steady approach, your credit will stay on track. And your home search will feel much smoother from start to finish.
Does getting pre approved for a mortgage hurt your credit score?
It can lower your score by a small amount because the lender makes a hard inquiry. The drop is usually minor and temporary, especially if you have a strong credit history.
How many points does a mortgage pre approval drop your score?
The change is often just a few points, though it can vary by person. Your overall credit profile, recent inquiries, and payment history all influence the exact impact.
Will multiple lenders checking my credit hurt me?
Not if you keep the applications close together. Most scoring models treat several mortgage inquiries in a short window as one event for rate shopping.
Does pre qualification affect credit the same way?
Usually not. Pre qualification often uses a soft pull or self reported details, so it does not impact your score the way a full pre approval does.
How long does a mortgage inquiry stay on your credit report?
A hard inquiry can remain on your report for up to two years. Its effect on your score fades much sooner as time passes and you maintain good habits.
Should I wait to apply for other credit during the process?
Yes, it is wise to hold off on new cards or loans until after closing. New debt can change your debt to income ratio and add another hard inquiry.
Frequently Asked Questions
What is Does Getting Pre Approved For A Mortgage Affect Your Credit?
Does Getting Pre Approved For A Mortgage Affect Your Credit is an important topic with many practical applications.