
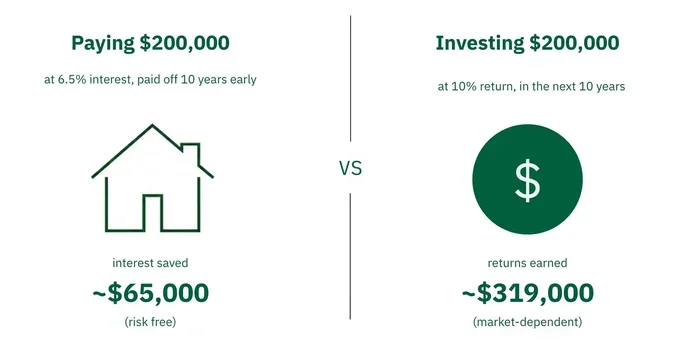
Deciding between paying off your mortgage early or investing your money is a big financial choice. A should I pay off my mortgage early or invest calculator can help you see the numbers clearly. This tool compares interest savings against potential investment growth. You will learn how to weigh risk, return, and peace of mind. Use this guide to make a smart plan for your money and your future.
Key Takeaways
- Understand your mortgage rate: Know your exact interest rate before comparing it to investment returns.
- Calculate potential gains: Use a should I pay off my mortgage early or invest calculator to see projected outcomes.
- Consider risk tolerance: Investing carries market risk, while paying debt offers guaranteed savings.
- Check for prepayment penalties: Some loans charge fees for paying off early, which affects your math.
- Build an emergency fund first: Keep cash saved for surprises before putting extra money toward debt or investments.
- Think about tax implications: Mortgage interest may be tax-deductible, while investment gains have different tax rules.
- Align with your goals: Choose the option that brings you closer to financial freedom and peace of mind.
📑 Table of Contents
- Should I Pay Off My Mortgage Early or Invest Calculator: Why This Question Matters
- Understanding Your Mortgage Rate and Loan Terms
- How a Should I Pay Off My Mortgage Early or Invest Calculator Works
- Comparing Guaranteed Savings vs. Market Growth
- Tax Considerations and After-Tax Returns
- Emotional Peace and Financial Flexibility
- Practical Steps to Run Your Own Comparison
- Expert Insights and Final Thoughts
Should I Pay Off My Mortgage Early or Invest Calculator: Why This Question Matters
Many people stand at a financial crossroads. They have extra cash each month. They wonder where it should go. Should it go toward the mortgage balance or into the stock market? This choice can shape your financial future for years. A should I pay off my mortgage early or invest calculator helps you see the path ahead. It turns a fuzzy feeling into clear numbers. That clarity matters when you plan for retirement, a new home, or your family’s security.
The decision is not just math. It is also about comfort. Some people hate debt. They sleep better when the house is paid off. Others want growth. They believe investments will beat loan interest over time. Both views have merit. Your personal situation guides the right answer. This article walks you through the key factors. You will learn how to use a calculator, what numbers to check, and how to think about risk. By the end, you will feel ready to make a confident choice.
Understanding Your Mortgage Rate and Loan Terms
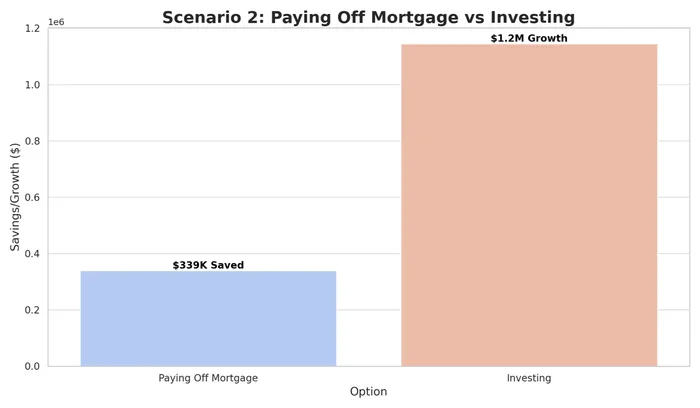
Your mortgage interest rate is the starting point. It tells you the cost of borrowing money for your home. If your rate is high, paying it down early saves more money. If your rate is low, the savings are smaller. You should also look at the loan term. A thirty-year loan gives you more time to invest. A fifteen-year loan builds equity faster. Each structure changes the math in a should I pay off my mortgage early or invest calculator.
Visual guide about mortgage payoff versus investing
Image source: cdn.chime.me
Fixed Rate vs. Adjustable Rate
A fixed-rate mortgage stays the same over time. You know exactly what you owe each month. This makes planning easier. An adjustable-rate mortgage can change after a set period. Your payment may rise later. That uncertainty can push some people to pay down the loan sooner. Others may prefer to invest and accept the risk. Your comfort with change matters here.
Prepayment Penalties and Hidden Costs
Some lenders charge a fee for early payoff. This is called a prepayment penalty. It can reduce or erase your savings. Always check your loan documents before making extra payments. You should also think about closing costs and refinance fees if you plan to change your loan. These costs affect the final numbers. A calculator can include these fees so you see the real picture.
How a Should I Pay Off My Mortgage Early or Invest Calculator Works
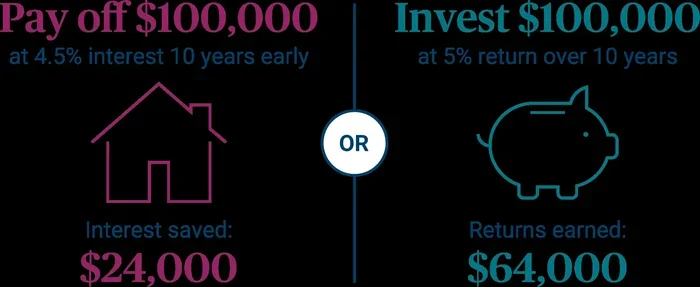
A should I pay off my mortgage early or invest calculator compares two paths. One path shows what happens when you pay extra on your loan. The other shows what happens when you invest that same money. The tool uses your interest rate, monthly payment, extra payment amount, and expected investment return. It then projects your balance over time. You can see which option leaves you with more wealth at the end.
Visual guide about mortgage payoff versus investing
Image source: cdn.ameriprisecontent.com
Key Inputs You Need
To get useful results, gather a few details first. You will need your current loan balance. You also need your interest rate and remaining term. Add the amount you can put toward the loan each month. Then choose an expected annual return for investing. Many people use a range, such as five to seven percent. This range reflects long-term market averages. The calculator turns these inputs into a side-by-side view.
Reading the Output
The results usually show two totals. One total is your interest saved from early payoff. The other is your investment growth over the same period. You may also see a net worth comparison. This helps you see which path builds more wealth. Some calculators also show a break-even point. That point tells you when one option starts to beat the other. Use this information to guide your choice, not to replace your judgment.
Comparing Guaranteed Savings vs. Market Growth
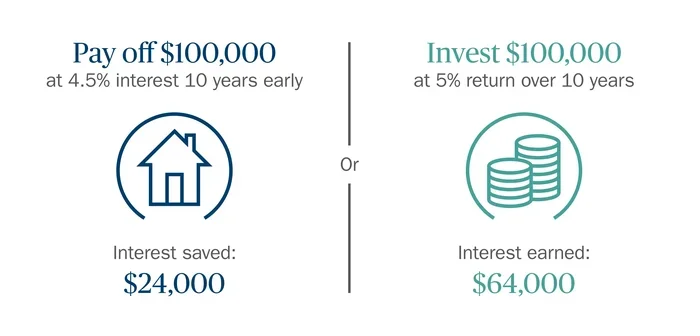
Paying off a mortgage gives you a guaranteed return. That return equals your interest rate. If your rate is six percent, you save six percent by paying early. There is no market risk in that savings. Investing offers potential growth, but it comes with ups and downs. The market can rise quickly or fall for a while. A should I pay off my mortgage early or invest calculator helps you compare these two very different outcomes.
Visual guide about mortgage payoff versus investing
Image source: ameriprise.com
The Risk Factor
Debt payoff is steady. You know the result in advance. Investing is less certain. Your returns depend on stock market performance, bond yields, and your asset allocation. Some years bring strong gains. Other years bring losses. If you can handle swings, investing may suit you. If you prefer calm and certainty, paying down the loan may feel better. Your risk tolerance is just as important as the numbers.
Time Horizon Matters
The length of time changes the result. A long time horizon gives investments more room to grow. Short-term goals often favor debt payoff. If you plan to move soon, building equity may matter more. If you plan to stay for decades, investing may compound nicely. Think about when you will need the money. That timeline helps you pick the better path.
Tax Considerations and After-Tax Returns
Taxes can shift the math. In some places, mortgage interest deductions reduce your taxable income. This lowers the real cost of your loan. If you deduct interest, your effective rate may be smaller. On the investment side, capital gains tax and dividend tax can reduce your returns. A should I pay off my mortgage early or invest calculator should account for these tax effects when possible. Even a rough estimate helps you compare after-tax outcomes.
Retirement Accounts and Tax Advantages
If you invest through a retirement account, you may get tax benefits. Some accounts let gains grow tax-deferred. Others allow tax-free withdrawals in retirement. These benefits can boost your effective return. That makes investing more attractive for some people. Still, you should compare the after-tax loan cost with the after-tax investment gain. The goal is to see what truly stays in your pocket over time.
Emotional Peace and Financial Flexibility
Money is not only math. It is also peace of mind. Some people feel heavy when they carry a large mortgage balance. Paying it off can bring relief. That relief has value. Other people feel better when they have liquid assets. Cash and investments can cover emergencies, opportunities, and life changes. A should I pay off my mortgage early or invest calculator shows the numbers, but your feelings matter too.
Building a Safety Net First
Before you choose, make sure you have a emergency fund. Life brings surprise repairs, job changes, and health costs. Cash in the bank gives you flexibility. If you put every extra dollar into your home, you may lack liquidity. That can create stress later. A balanced plan often works best. You can pay some extra on the loan while still keeping savings accessible.
When Paying Off Early Makes Sense
Early payoff often feels right when your interest rate is high. It also helps if you want to reduce monthly obligations before retirement. Some people aim to own their home outright before they stop working. That can lower their needed income in later years. If that goal matters to you, the calculator can show how fast you can get there. It can also show the cost of waiting.
When Investing May Be the Better Choice
Investing may win when your loan rate is low and your expected returns are higher. It may also suit you if you already have a paid-off home or a small balance. In that case, extra cash can work harder in a diversified portfolio. Investing also helps you build wealth beyond your house. That can support retirement, education, or other life goals. The calculator can show how much extra wealth you might create.
Practical Steps to Run Your Own Comparison
You do not need fancy software to start. You can use a simple spreadsheet or an online tool. Begin by listing your current loan details. Then choose a monthly extra payment you can afford. Next, pick a realistic investment return assumption. Run the numbers for five, ten, and twenty years. Compare the results at each stage. This gives you a fuller picture than a single snapshot.
Quick Tips for Better Decisions
- Check your rate first: A higher rate usually favors payoff.
- Use a range of returns: Try conservative and optimistic investment estimates.
- Include taxes: Estimate after-tax results for both paths.
- Keep liquidity in mind: Do not drain your emergency savings.
- Revisit often: Life changes, and your plan should too.
Common Mistakes to Avoid
- Ignoring fees: Prepayment penalties can change the outcome.
- Assuming high returns: Overly optimistic estimates can mislead you.
- Forgetting taxes: After-tax numbers tell the real story.
- Comparing only one year: Long-term views reveal the true difference.
- Skipping emergency savings: Liquidity protects you from stress.
Expert Insights and Final Thoughts
Financial choices work best when they fit your life. A should I pay off my mortgage early or invest calculator gives you a strong starting point. It turns guesses into comparisons. Yet the best answer also includes your comfort, your goals, and your timeline. Some people value a debt-free home. Others value growth and flexibility. Both are valid. The key is to choose on purpose.
You can also blend the two approaches. Put some extra money toward the loan and some toward investments. That way, you gain steady progress on both fronts. You reduce debt while still building wealth. This balanced path often feels manageable. It also keeps options open if your situation changes. Review your plan each year. Adjust as your income, rates, or goals shift.
In the end, the right move is the one that supports your future and your peace of mind. Use the calculator to see the numbers. Then trust your judgment to choose what feels right. With a clear plan, you can move forward with confidence. Your money can work for you in a way that matches your life.
Frequently Asked Questions
What does a should I pay off my mortgage early or invest calculator compare?
It compares the interest you save by paying down your loan with the growth you might earn by investing the same money. The tool helps you see which option may build more wealth over time.
How do I choose the right investment return rate for the calculator?
Use a realistic long-term estimate based on your portfolio. Many people test a range of returns so they can see both conservative and optimistic outcomes.
Does paying off my mortgage early always save more money?
Not always. If your interest rate is low and investments perform well, investing may produce better results. The calculator helps you compare the two paths with your actual numbers.
Should I keep an emergency fund before paying off my mortgage?
Yes. An emergency fund gives you cash for surprise costs and life changes. It is wise to keep savings accessible before using extra money for debt payoff.
What if my mortgage has a prepayment penalty?
A prepayment penalty can reduce your savings from early payoff. Check your loan terms first, then include any fees in your comparison so the numbers stay accurate.
Can I do both payoff and investing at the same time?
Yes. Many people split extra cash between the mortgage and investments. This balanced approach can reduce debt while still building wealth for the future.