
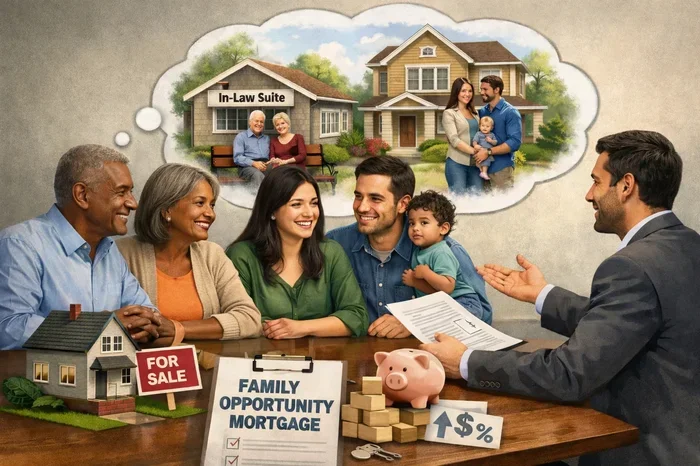
Assuming a mortgage from your parents can save you money and keep your family home in the family, but it is not always simple. Lenders must approve the transfer, and you will need to meet credit and income requirements. Understanding the process, costs, and risks helps you decide if this path is right for your situation.
This is a comprehensive guide about Can I Assume A Mortgage From My Parents.
Visual guide about family home mortgage discussion
Image source: f5mortgage.com
Visual guide about family home mortgage discussion
Image source: imgcdn.stablediffusionweb.com
Visual guide about family home mortgage discussion
Image source: t3.ftcdn.net
Key Takeaways
- Assumable loans are rare: Most modern mortgages are not assumable without lender approval.
- Lender consent is required: You must qualify financially before the loan can transfer to your name.
- Due-on-sale clauses matter: Many loans trigger full repayment if ownership changes without permission.
- Costs still apply: You may face appraisal fees, title work, and assumption processing charges.
- Credit and income checks are strict: Lenders will review your debt-to-income ratio and credit history.
- Family agreements need paperwork: Clear contracts protect both parents and the new borrower.
- Professional guidance helps: A real estate attorney or loan officer can clarify your options.
[FEATURED_IMAGE_PLACEHOLDER]
Understanding Can I Assume a Mortgage from My Parents
Many people ask can I assume a mortgage from my parents when they want to keep a family home and avoid a new loan. The idea sounds simple. You take over the existing payments and keep the same interest rate. In practice, the process depends on the loan type, the lender, and your financial profile. This guide breaks down what you need to know before you move forward.
Family home transfers happen for many reasons. Parents may want to help a child buy a house without a large down payment. Others want to pass down a property while keeping the current loan terms. These goals are understandable. Still, lenders protect their interests. They want to know the new borrower can handle the payments. That is why approval matters.
You should start by learning the basics of loan assumptions. An assumption means you take over the remaining balance, interest rate, and repayment schedule. You do not create a brand new loan. That can be a big advantage if the current rate is lower than market rates. It can also save on closing costs. But the lender must agree to the transfer. Without that approval, the deal cannot move forward safely.
What an Assumption Really Means
An assumption is a formal transfer of responsibility. The original borrower steps out, and the new borrower steps in. The lender reviews the new borrower’s credit, income, and debt. If everything looks strong, the lender may allow the transfer. Some loans are easier to assume than others. Government-backed loans often have clearer rules. Conventional loans can be stricter.
It helps to think of an assumption as a two-part process. First, the lender checks whether the loan is eligible. Second, the lender checks whether you are eligible. Both parts must pass. If either part fails, the assumption stops. That is why you should not assume anything is automatic. Even transfers between family members need proper review.
Why Families Consider This Path
Families often look at assumptions for practical reasons. The current interest rate may be much lower than today’s market rates. The remaining balance may fit the child’s budget better than a new mortgage. Parents may also want to help without giving a large cash gift. In some cases, the home has sentimental value. Keeping it in the family feels important.
There are also financial benefits to weigh. Assumption fees are often lower than full closing costs. You may avoid some of the fees tied to a new loan. You also keep the original amortization schedule. That can mean faster equity buildup if the loan is already mature. These advantages make assumptions attractive when the numbers line up.
Loan Types and Assumability Rules
Not every loan can be assumed. The loan type matters a lot. Some loans are designed to be transferable. Others are not. If you want to know can I assume a mortgage from my parents, you must first identify the loan. The paperwork will tell you what is allowed.
Government-backed loans often have clearer assumption paths. FHA loans and VA loans are common examples. These loans may allow assumptions under specific conditions. USDA loans can also have assumable features. The rules vary, so you need to check the original loan documents. Lender approval is still part of the process.
Conventional loans are different. Many modern conventional mortgages include a due-on-sale clause. That clause lets the lender demand full repayment when ownership changes. In other words, the loan may not be transferable without the lender’s consent. Some older conventional loans are more flexible. That is why the loan’s age and terms matter.
FHA and VA Loan Considerations
FHA loans are often more assumable than conventional loans. A qualified buyer may take over the loan if the lender approves the credit and income review. VA loans can also be assumable, but there are important safeguards. The veteran’s benefit status may be affected if the assumption is not handled correctly. That means both sides should understand the impact before signing anything.
These programs can be helpful for families. They often offer more structured assumption processes. They also set clear eligibility standards. That can make planning easier. Still, you should not guess. Read the loan documents and ask the lender directly.
Conventional Loans and Due-on-Sale Clauses
Conventional loans are the most common type of mortgage today. Many of them include a due-on-sale clause. This clause gives the lender the right to call the loan due if the property transfers without permission. That does not mean every transfer is blocked. It does mean you need lender cooperation.
If the loan has this clause, the assumption may require full lender approval. The lender may allow it if the new borrower qualifies. The lender may also prefer a refinance instead. That is a key point. Sometimes the lender would rather issue a new loan than approve an assumption. You should be ready for either outcome.
The Approval Process Step by Step
If you are wondering can I assume a mortgage from my parents, the answer usually depends on the approval process. The lender needs to see that the new borrower can repay the loan. This review looks a lot like a normal mortgage application. You will provide income details, credit information, and debt details. The lender then decides if the transfer makes sense.
The first step is to contact the loan servicer. Ask whether the loan is assumable. Ask what documents are needed. Ask about fees and timelines. Some lenders have a specific assumption package. Others handle it case by case. Getting clear answers early saves time.
Next, gather your financial records. You will likely need pay stubs, tax returns, bank statements, and proof of assets. The lender may also pull your credit. Be ready to explain any unusual items on your credit report. A clean, organized file helps the review move faster.
Documents You Will Likely Need
Lenders want a full picture of your finances. Common documents include:
- Proof of income, such as pay stubs or tax returns
- Bank statements showing available funds
- A list of monthly debts and obligations
- Identification and residency details
- The current loan information and property details
Parents may also need to provide documents. They may need to show the original loan terms and proof of ownership. If the property title needs updating, the lender may request more paperwork. Title work can be part of the process. So can an appraisal or valuation review.
Timeline and What to Expect
Assumptions are not always fast. The timeline depends on the lender and the loan type. Some reviews take a few weeks. Others take longer. You should plan for delays. Do not count on a quick close unless the lender confirms it.
During the review, stay responsive. Answer questions quickly. Provide missing documents as soon as possible. If the lender requests an appraisal or title update, cooperate fully. Small delays can stack up. Clear communication keeps the process moving.
Costs, Risks, and Hidden Hurdles
People often focus on the benefit of a low rate. That is important. But you should also look at the costs and risks. Even a friendly family transfer can create financial strain if you do not plan carefully. The question can I assume a mortgage from my parents is not only about eligibility. It is also about whether the deal is wise.
Assumption fees can add up. You may pay for processing, title work, recording, and possibly an appraisal. Some lenders charge a review fee. These costs are usually lower than a full refinance, but they are not zero. You should ask for a fee estimate before you commit.
There are also risks to consider. If the assumption is not done correctly, the original borrower may remain liable. That can be a serious problem for parents. It can also affect your relationship if money issues arise later. A clear agreement and proper release documents matter a lot.
Liability and Release Concerns
One of the biggest concerns is liability. If the lender does not release the original borrower, the parents may still be on the hook. That means missed payments could hurt their credit too. This is why written lender approval is so important. You want a clean break, not a vague handshake deal.
Family deals can also blur boundaries. A child may assume payments will be easy. Parents may assume the child will always keep up with the bill. Those assumptions can cause conflict. Put the agreement in writing. Define who pays what. Explain what happens if circumstances change.
When an Assumption May Not Be the Best Choice
An assumption is not always the best move. If the loan has a high balance and your income is limited, the payment may still be too heavy. If the house needs major repairs, you may need extra cash. If the lender refuses the assumption, you may need a different path. In those cases, a refinance or a new purchase loan could make more sense.
It also helps to compare options. A new loan might offer better terms in some situations. A refinance could lower the payment if rates have changed. The right choice depends on your numbers. Do not choose an assumption just because it sounds simpler. Check the math first.
How to Protect Both Sides in a Family Transfer
Family transactions work best when everyone is clear. Parents want to help, but they also want protection. Children want the home, but they also want realistic terms. A good process respects both goals. If you are asking can I assume a mortgage from my parents, you should also ask how to make the transfer safe and fair.
Start with open conversations. Talk about the payment, taxes, insurance, repairs, and long-term plans. Discuss what happens if someone cannot pay. Discuss whether the child will own the home alone or whether other family members have an interest. These talks may feel awkward, but they prevent bigger problems later.
Then use proper paperwork. A simple promise is not enough. You need lender approval, title updates, and a clear record of the transfer. If the parents are gifting equity or helping with costs, document that too. Written terms reduce confusion. They also help if questions come up later.
Legal and Title Basics
Title transfer is a separate step from loan assumption. The lender may approve the loan, but the title still needs to reflect the new owner. That usually means recording a new deed or other ownership document. Local rules vary, so you should follow the correct process in your area.
It is also wise to review any existing liens, easements, or obligations tied to the property. These items can affect the transfer. A title search can reveal surprises before closing. Finding them early is much better than discovering them after the deal is done.
Communication Tips for Families
Money talks can get emotional. Keep the conversation practical. Focus on facts, not feelings. Use a simple checklist. Cover the payment amount, due date, maintenance budget, and emergency fund. If helpful, write the plan together and both sign it.
If tension rises, bring in a neutral professional. A loan officer, real estate attorney, or financial advisor can explain the rules without taking sides. That can make the discussion calmer. It can also keep the family relationship healthier.
Alternatives if the Assumption Is Not Allowed
Sometimes the lender says no. Other times the loan is simply not assumable. If that happens, do not panic. There are other ways to keep the home or move forward responsibly. The question can I assume a mortgage from my parents may still have a different answer: not directly, but perhaps through another path.
One option is a refinance in your name. This creates a new loan, but it can still help you keep the property. You may be able to choose a term and rate that fit your budget. Another option is a purchase loan if the parents sell the home to you. That path may involve a new mortgage, but it can be clean and straightforward.
A third option is a formal family agreement with careful legal structure. This may involve a title transfer and a separate financing arrangement. These deals can work, but they need strong documentation. They also need to respect lender rules. A professional can help you avoid mistakes.
Refinance vs Assumption Comparison
Here is a simple comparison to help you think through the choice:
- Assumption: Keeps the existing rate and balance, may cost less to process, requires lender approval, and may not be available for all loans.
- Refinance: Creates a new loan, may offer a different rate or term, can require more closing costs, and gives you a fresh start in your own name.
- Purchase loan: Works well if the parents sell the home to you, involves a new mortgage, and may be simpler if the assumption path is blocked.
Each path has tradeoffs. The best choice depends on the loan, the rate, the budget, and the family goals. Compare the total cost, not just the monthly payment. Look at the long-term impact too.
Final Thoughts on Taking Over a Parent’s Mortgage
The short answer to can I assume a mortgage from my parents is that it depends. Some loans are assumable. Some lenders will approve a qualified family member. Some will not. The process takes paperwork, patience, and careful planning. When it works, it can preserve a low rate and keep a family home stable. When it does not work, other options may still be available.
If you want to move forward, start with the loan documents. Contact the servicer. Ask direct questions. Gather your financial records. Review the costs and risks before you commit. Most of all, make sure the transfer is done properly so both sides are protected. A family home is worth handling with care.
Key Takeaways
- Check the loan type first: Assumability depends on the original mortgage terms.
- Get lender approval in writing: Verbal permission is not enough.
- Review costs and liability: Fees, title work, and release terms matter.
- Compare alternatives: Refinance or purchase loans may be better in some cases.
- Use clear family agreements: Written plans reduce conflict and confusion.
Frequently Asked Questions
Can I assume a mortgage from my parents without lender approval?
No, you generally cannot. The lender must approve the transfer, and the loan must allow assumption. Without approval, the transfer may violate the loan terms.
Do all mortgages allow assumptions?
No, many modern mortgages do not. Some government-backed loans may be assumable, while many conventional loans include a due-on-sale clause. Always check the original loan documents.
Will I need to qualify financially to assume the loan?
Yes, in most cases. The lender will review your credit, income, and debt-to-income ratio. You must show that you can handle the payments.
Are assumption costs lower than refinancing?
Often they are, but not always. You may still pay processing, title, and recording fees. Ask the lender for a written estimate before you decide.
Can parents remain liable after the assumption?
They should not if the lender properly releases them. If the loan is not handled correctly, the original borrowers may still be responsible. Get everything in writing.
What if my parents’ loan is not assumable?
You may need to refinance, buy the home with a new loan, or use another structured option. A loan officer or attorney can help you compare the best path.