
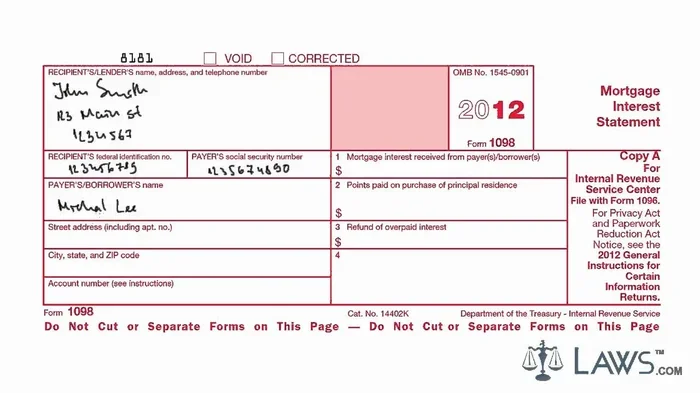
Discovering that your mortgage company didn’t pay your property taxes can be incredibly stressful and confusing. This issue often stems from escrow account errors, processing delays, or simple administrative oversights that put your home at risk. In this guide, we will walk you through exactly why this happens, what immediate steps you must take to protect your property, and how to ensure it never happens again. Acting quickly is crucial to avoid penalties, liens, or even foreclosure threats.
This is a comprehensive guide about My Mortgage Company Didnt Pay My Property Taxes.
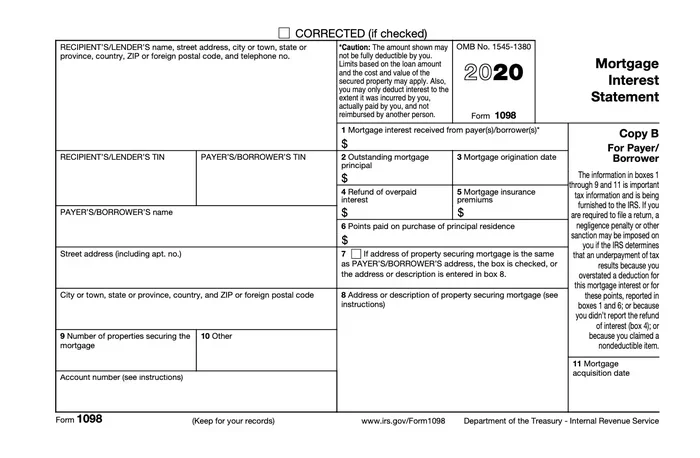
Visual guide about house mortgage tax documents
Image source: investopedia.com
Visual guide about house mortgage tax documents
Image source: homelight.com
Visual guide about house mortgage tax documents
Image source: districtlending.com
Key Takeaways
- Immediate Action Required: Contact your mortgage servicer right away to confirm if the payment was missed or just delayed.
- Escrow Account Errors: Many tax payment failures stem from incorrect escrow analysis or missing funds in your escrow account.
- Tax Liens Pose Serious Risk: Unpaid property taxes can lead to tax liens, penalties, and eventually foreclosure if ignored.
- Lender Liability: Mortgage companies are generally legally required to pay taxes from escrow, making them liable for errors.
- Document Everything: Keep detailed records of all communications, payments, and correspondence with your lender.
- Set Up Independent Monitoring: Consider paying taxes directly if your lender repeatedly fails to manage escrow correctly.
- Know Your Deadlines: Property tax due dates are strict, and late fees accumulate quickly regardless of lender mistakes.
[FEATURED_IMAGE_PLACEHOLDER]
Introduction
Finding out that your mortgage company didn’t pay your property taxes can feel like a massive headache. You pay your monthly mortgage payment on time every single month. You assume your lender handles the rest. But when tax season arrives, you might receive a notice from your local tax authority. This notice can be scary. It might mention late fees, penalties, or even a tax lien. You wonder what went wrong. You also worry about your home.
This situation is more common than many homeowners realize. Mortgage servicers manage escrow accounts for millions of properties. Sometimes, mistakes happen. These mistakes can range from simple processing delays to serious escrow calculation errors. Regardless of the cause, the responsibility to fix it falls on you initially. You need to act fast. Property tax authorities do not care about your mortgage company’s internal issues. They want their money on time.
In this article, we will break down everything you need to know. We will explain why this happens. We will show you exactly what steps to take right now. We will also discuss how to protect yourself in the future. You will learn about escrow accounts, lender responsibilities, and your rights as a homeowner. By the end, you will feel confident and ready to handle this challenge.
Why Did My Mortgage Company Miss My Property Tax Payment?
Understanding the root cause is the first step. There are several common reasons why a mortgage servicer might fail to pay your property taxes on time. One frequent cause is an escrow account shortage. Your monthly mortgage payment includes a portion for taxes. The lender puts this money into an escrow account. If the tax bill increases and the lender did not adjust your monthly payment quickly enough, the account might not have enough funds. The lender might attempt to pay the tax bill and face a shortfall.
Another common reason is administrative error. Mortgage companies handle massive volumes of payments every day. A simple data entry mistake can cause a tax payment to be missed. The address might be wrong. The tax ID number might be incorrect. The payment might get stuck in processing. Sometimes, the lender simply forgets to schedule the payment before the deadline. These errors are frustrating, but they do happen.
Changes in property tax assessments can also create confusion. Local governments sometimes reassess property values. This leads to a higher tax bill. If the new bill is much larger than expected, the escrow account might not cover it. The lender might delay paying the difference until they can collect more from you. During this delay, the tax authority might mark the bill as unpaid. You might also have a change in ownership or exemption status that the lender did not update. This can cause the tax bill to go to the wrong place or be calculated incorrectly.
What Immediate Steps Should You Take Right Now?
Time is critical when property taxes are unpaid. You should take immediate action to prevent penalties from growing. First, contact your mortgage servicer right away. Call the customer service number on your mortgage statement. Ask specifically about your property tax escrow account. Confirm whether the payment was sent, when it was sent, and if it has cleared. Ask for a copy of the payment confirmation or the check number. If they say the payment is pending, ask for a specific date when it will be sent.
Second, contact your local tax authority directly. Call the county tax assessor or collector’s office. Explain that your mortgage company is supposed to pay the taxes. Provide them with your mortgage servicer’s name. Ask if a payment is expected soon. Sometimes, tax offices will place a temporary hold on penalties if they know a lender is handling the payment. This can buy you some time. You should also ask for the exact amount owed and the final deadline to avoid serious consequences.
Third, gather all your documents. Collect your mortgage statements, escrow analysis reports, and previous tax bills. Write down the dates and names of everyone you speak with. Keep a log of every phone call and email. This documentation will be vital if you need to dispute the issue later. You should also check your online mortgage account portal. Many servicers show escrow activity and payment history there. Look for any pending transactions or alerts about insufficient funds.
Understanding Escrow Accounts and Lender Responsibilities
Most homeowners with mortgages have escrow accounts. These accounts are designed to make property tax and insurance payments easier. Instead of paying a huge tax bill once a year, you pay a smaller amount each month with your mortgage. The lender holds this money and pays the tax bill when it is due. This system protects the lender’s interest in the property. It also helps homeowners budget for large expenses.
Lenders have a legal and contractual responsibility to pay property taxes from the escrow account. Your mortgage agreement usually includes a clause requiring the lender to pay taxes to protect their lien on the home. If the lender fails to pay, they are technically in breach of this duty. However, the lender’s obligation is usually tied to having sufficient funds in the escrow account. If the account has enough money and the lender still misses the payment, the lender is clearly at fault. If the account is short, the lender might argue that they need more time to collect the shortage from you.
The Real Estate Settlement Procedures Act (RESPA) provides some protections for homeowners with escrow accounts. RESPA requires lenders to analyze escrow accounts annually. They must send you a statement showing projected disbursements and any shortages. If your taxes increased, the lender should adjust your monthly payment accordingly. Understanding these rules helps you know when your lender is following the law and when they might be making a mistake. You can use this knowledge to hold your servicer accountable.
How to Protect Your Home From Tax Liens and Penalties
Unpaid property taxes can lead to serious consequences. Local governments can place a tax lien on your property. A tax lien is a legal claim against your home for unpaid taxes. This lien can hurt your credit score. It can also make it difficult to sell or refinance your home. In extreme cases, persistent unpaid taxes can lead to a tax foreclosure. This means the government could eventually take your property to satisfy the debt. While this is rare when a mortgage is involved, the risk is real if the issue is ignored for too long.
To protect your home, you must stay proactive. If your mortgage company confirms they will pay the bill, follow up to ensure the payment clears. Do not assume the problem is solved after one phone call. Check your tax authority’s online portal or call them again a few days later. Verify that the payment was received and applied to your account. If the lender cannot pay immediately, ask if you can pay the tax bill directly yourself. Some lenders allow this in emergency situations. You would then be reimbursed from the escrow account later, or the lender would adjust your future payments.
You should also consider setting up your own reminders. Even if your lender handles taxes, you should monitor the due dates. Mark the tax deadline on your calendar. Check your escrow account balance a month before the due date. If the balance looks low, contact your lender early. Catching a potential shortage early gives the lender time to adjust your payments or request additional funds. This simple habit can prevent many headaches down the road.
When to Escalate the Issue or Pay Taxes Directly
Sometimes, your mortgage company might not resolve the issue quickly. They might give you the runaround. They might claim the payment is pending for weeks. In these cases, you may need to escalate the problem. Start by asking for a supervisor or the escrow department manager. Explain the urgency clearly. Mention that tax penalties are accumulating and your home is at risk. Put your concerns in writing. Send a certified letter to the lender’s dispute department. This creates a formal record and often speeds up the process.
If the lender continues to fail, you might consider paying the taxes yourself. This is a last resort, but it protects your home immediately. Contact your tax authority and pay the bill directly. Keep the receipt and all proof of payment. Then, notify your mortgage company that you paid the taxes. Request that they reimburse you from the escrow account or credit your account. You should also check your mortgage agreement to see if direct payment is allowed. Some lenders have specific procedures for this situation.
If the lender refuses to reimburse you or fix the escrow account, you can file a complaint. You can contact the Consumer Financial Protection Bureau (CFPB). The CFPB handles complaints about mortgage servicers and escrow issues. You can also contact your state’s banking or real estate regulator. These agencies can investigate and pressure the lender to correct the error. Escalation is stressful, but it is sometimes necessary to get results.
Common Mistakes Homeowners Make During Escrow Disputes
Many homeowners make mistakes that worsen the situation. One common mistake is ignoring the problem. Some people hope the lender will fix it on their own. This is risky. Penalties and interest keep adding up. Another mistake is not keeping records. If you do not write down who you spoke with and when, it is hard to prove your case later. You might also fail to check your escrow statements regularly. These statements show if your account is short or if payments are missing.
Another mistake is assuming the lender is always right. Mortgage companies make errors. They might use the wrong tax amount. They might send payment to the wrong address. You should verify the tax bill amount yourself. Compare it with what the lender says they paid. Do not rely solely on the lender’s word. You should also avoid paying late fees without documenting the reason. If you pay a penalty because the lender missed the deadline, keep the receipt. You may be able to demand reimbursement later.
Quick Tips for Handling Tax Payment Issues:
- Call your lender immediately when you suspect a missed payment.
- Keep a detailed log of every conversation and email.
- Verify the tax amount with your local tax office directly.
- Ask for written confirmation of any payment promises.
- Check your escrow account balance monthly.
- Set calendar reminders for property tax due dates.
- Consider paying directly if the lender delays too long.
Expert Insights on Escrow Management:
- Monitor Your Escrow Analysis: Review your annual escrow statement carefully. Look for shortages or incorrect projections.
- Communicate in Writing: Always follow up phone calls with an email or letter. This creates a paper trail.
- Know Your Local Laws: Some states have specific rules about escrow payments and lender liability. Research your local regulations.
- Build a Relationship with Your Tax Office: A friendly relationship with your tax collector can help you get accurate information quickly.
- Stay Calm but Firm: Lenders respond better to clear, professional demands than to angry threats. Be persistent and polite.
Frequently Asked Questions
What should I do if my mortgage company says they paid my taxes but the tax office says they didn’t receive it?
Ask your mortgage company for the payment tracking number, check number, and the exact date the payment was sent. Then, provide this information to your tax office and ask them to trace the payment. Sometimes payments get lost in the mail or applied to the wrong account, and this information helps resolve the issue quickly.
Can my lender be held responsible if they fail to pay my property taxes on time?
Yes, lenders are generally contractually and legally required to pay property taxes from your escrow account if sufficient funds are available. If they fail to pay despite having the money, you may be able to demand reimbursement for penalties and request corrective action. Document everything and escalate to a supervisor or regulatory agency if needed.
Will a missed property tax payment affect my credit score?
A missed payment itself usually does not hit your credit score immediately, but if it leads to a tax lien, that lien can be reported and damage your credit. Tax liens are serious public records that lenders and creditors can see, so it is important to resolve the issue before a lien is filed.
How can I check if my escrow account has enough money for my property taxes?
Review your annual escrow analysis statement provided by your lender. This document shows your projected tax and insurance payments, your current escrow balance, and whether you have a shortage or surplus. You can also log into your online mortgage account to see recent escrow transactions and balances.
What happens if I pay my property taxes directly instead of waiting for my mortgage company?
Paying directly can protect your home from penalties and liens while you resolve the escrow issue. You should keep all receipts and notify your lender immediately so they can reimburse you from the escrow account or adjust your future payments. Check your mortgage agreement to ensure direct payment is allowed in your situation.
How long does it take for a mortgage company to fix an escrow payment error?
The time varies depending on the lender and the complexity of the error. Simple payment delays might be resolved in a few days, while escrow shortages or administrative mistakes could take several weeks. Follow up regularly and request written updates to keep the process moving.
Conclusion
Dealing with a situation where your mortgage company didn’t pay your property taxes is stressful, but it is manageable if you act quickly. Start by contacting your lender and your tax office right away. Gather your documents and keep detailed records of every step. Understand how your escrow account works and know your rights under RESPA and your mortgage agreement. Protect your home by verifying payments and following up until the issue is fully resolved.
If your lender is slow to respond, escalate the issue or consider paying the taxes yourself to avoid liens and penalties. Stay proactive by monitoring your escrow balance and marking tax deadlines on your calendar. With the right approach, you can fix this problem and prevent it from happening again. Your home is worth the effort, and taking control of the situation will give you peace of mind.
Frequently Asked Questions
What is My Mortgage Company Didnt Pay My Property Taxes?
My Mortgage Company Didnt Pay My Property Taxes is an important topic with many practical applications.