
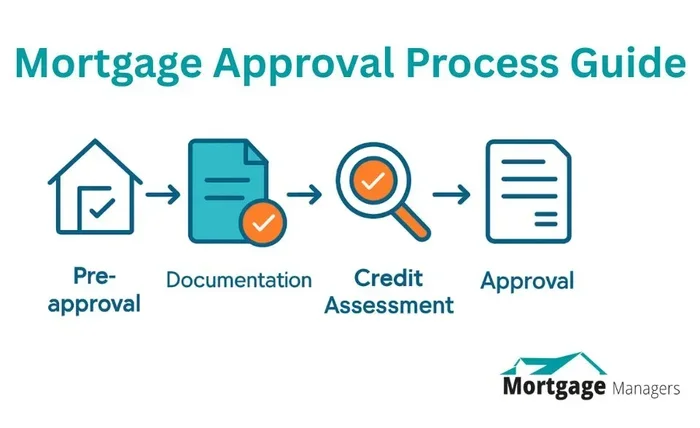
When you apply for a home loan, lenders look closely at your finances. Most banks use gross income as the starting point for mortgage approval. But they also check your net income, debts, and spending habits. This guide explains exactly how banks review your earnings. You will learn what papers to gather and how to present your finances in the best light.
This is a comprehensive guide about Do Banks Use Gross Or Net Income For Mortgage.

Visual guide about mortgage approval document review
Image source: texasunitedmortgage.com

Visual guide about mortgage approval document review
Image source: marketing.gmccloan.com

Visual guide about mortgage approval document review
Image source: homesteadfinancial.com
Key Takeaways
- Gross income is the baseline: Lenders start with your total pay before taxes and deductions.
- Net income matters too: Banks check your take-home pay to see if you can cover monthly bills.
- Debt-to-income ratio is key: Your gross income helps calculate this ratio, which affects approval.
- Stable employment helps: A steady job history makes lenders feel safer about your income.
- Self-employed borrowers face more review: Banks may ask for extra tax forms and profit records.
- Bonuses and overtime count: Lenders often average these over two years to include them.
- Prepare your documents early: Pay stubs, tax returns, and bank statements speed up the process.
[FEATURED_IMAGE_PLACEHOLDER]
Do Banks Use Gross or Net Income for Mortgage?
Buying a home is one of the biggest money steps you will take. You want clear answers before you sign papers. The first question many buyers ask is simple. Do banks use gross or net income for mortgage decisions? The short answer is that lenders start with your gross income. But they do not stop there. They also look at your net pay, your debts, and your spending habits. This mix helps them see if you can handle a monthly mortgage payment.
Think of it like a puzzle. Your gross income is the big picture on the box. Your net income, debts, and job stability are the pieces. Lenders put the pieces together to judge risk. They want to know if you can pay on time for years to come. If you understand how they review your money, you can get ready with less stress. You can also avoid surprises that slow down your approval.
This guide breaks the process into simple parts. You will learn what gross income means in a mortgage review. You will also see how net income fits into the picture. We will cover the debt-to-income ratio, special cases like bonuses, and tips for self-employed buyers. By the end, you will know what to gather and how to present your finances with confidence.
Gross Income: The Starting Point for Lenders
Gross income is the total amount you earn before any cuts. It includes your base pay, hourly wages, commissions, and tips. It also includes bonuses and overtime if they are part of your regular earnings. Lenders like gross income because it is easy to measure. It gives them a clear starting number for your earning power.
When you fill out a loan application, you will list your gross income. The lender will compare that number to your monthly debts. This step helps them see how much room you have for a mortgage payment. They also use gross income to calculate your debt-to-income ratio. That ratio is a major factor in approval decisions.
Here is a simple example. If you earn 5,000 dollars gross each month and your debts total 1,500 dollars, your ratio is 30 percent. That is a healthy number for many lenders. If your debts rise to 2,500 dollars, your ratio jumps to 50 percent. That can raise red flags. So gross income sets the stage, but your debts shape the final result.
Quick Tips:
– Gather recent pay stubs that show your gross pay.
– Include all regular income sources, not just your base salary.
– Be ready to explain any large changes in your pay.
Common Mistakes:
– Listing only take-home pay and ignoring gross pay.
– Forgetting to include consistent overtime or bonuses.
– Leaving out side income that appears on tax returns.
Net Income and Why It Still Matters
Net income is what lands in your bank account after taxes and deductions. It is your take-home pay. Lenders do not use net income as the main number for approval. But they still care about it. Why? Because it shows how much cash you actually have to live on. A mortgage payment is just one part of your monthly budget. You also need money for food, utilities, transport, and savings.
Banks review your net income to check your real-world cash flow. They want to see that you can pay your mortgage and still cover life expenses. If your gross income looks high but your net pay is very low due to heavy deductions, lenders may ask questions. They might look closer at your pay stubs and tax forms. They may also check your bank statements to see how money moves through your accounts.
Net income becomes more important if your pay structure is complex. For example, if you have large retirement contributions or garnishments, your take-home pay may be much lower than your gross pay. Lenders will note this. They want to be sure your monthly budget is realistic. A strong gross income is great, but a workable net income keeps the lights on.
Expert Insights:
– Lenders often compare your gross income to your net income to spot big deductions.
– Large, non-essential deductions may be added back in some cases, but not always.
– Your bank statements can help show steady cash flow and responsible spending.
How the Debt-to-Income Ratio Connects Gross Income to Approval
The debt-to-income ratio, or DTI, is one of the most important numbers in a mortgage review. It compares your gross income to your monthly debt payments. This ratio tells lenders how much of your income is already committed. A lower ratio usually means a stronger application. A higher ratio can make approval harder or lead to a smaller loan amount.
There are two common types of DTI. The front-end ratio looks at housing costs only. It includes your future mortgage payment, taxes, insurance, and any HOA fees. The back-end ratio looks at all your monthly debts. That includes car loans, student loans, credit cards, and the new mortgage payment. Lenders often focus on the back-end ratio because it shows your full financial load.
Many lenders prefer a back-end ratio around 36 percent or lower. Some programs allow higher ratios, especially with strong credit or a larger down payment. But a lower ratio usually gives you more options. It can also help you qualify for better rates. That is why gross income matters so much. It is the number used to measure this ratio.
Quick Tips:
– Pay down small balances before you apply to lower your DTI.
– Avoid opening new credit cards or loans right before your mortgage review.
– Ask your lender which DTI target they aim for with your loan program.
Common Mistakes:
– Counting future mortgage costs incorrectly in your ratio.
– Forgetting recurring debts like child support or alimony.
– Assuming a high gross income alone will offset high debts.
Special Income Types: Overtime, Bonuses, and Self-Employment
Not every income source is the same. Lenders treat regular base pay in a standard way. But they handle overtime, bonuses, commissions, and self-employment differently. They want proof that your income is stable and likely to continue. That is why they often look at a two-year history for these income types.
For overtime and bonuses, lenders may average them over the last two years. If your overtime is consistent, they might include it fully. If it varies a lot, they may use a smaller amount or leave it out. The goal is to use a number that is realistic for the future. They do not want to approve a loan based on a one-time spike.
Self-employment adds more review. Lenders usually ask for two years of tax returns. They look at your net business income after expenses. They may also review profit and loss statements. If your business income jumps up and down, they may use the lower year. This can feel frustrating, but it is about risk. A steady record helps your case.
If you are self-employed, keep your records clean. Separate business and personal expenses. Track your income clearly. Work with a tax professional who understands how lenders view your returns. A well-kept file can make the review smoother.
Expert Insights:
– Lenders usually want a two-year history for variable income.
– Consistent patterns matter more than a single strong year.
– Clean records and clear paperwork can speed up the review.
Documents You Need and How to Prepare
Good paperwork makes the process faster and less stressful. Lenders need proof of your income, your debts, and your assets. The exact list can vary by loan program, but the basics are similar. Having these ready before you apply shows you are organized. It also helps your lender give you a clear answer sooner.
Common documents include recent pay stubs, W-2 forms, and tax returns. If you are self-employed, you may need business tax returns and a profit and loss statement. Bank statements are also important. They show your cash reserves and spending habits. Lenders may ask for statements from the last two months. They want to see steady deposits and reasonable balances.
You should also gather proof of your debts. This includes loan statements, credit card balances, and any court-ordered payments. If you have alimony or child support, be ready to show the terms. Clear documents help the lender calculate your debts correctly. That leads to a more accurate DTI and a smoother review.
Quick Tips:
– Make digital copies of every document in case you need them again.
– Check that names and addresses match across all forms.
– Update your lender quickly if anything changes during the process.
Common Mistakes:
– Submitting blurry or incomplete documents.
– Leaving out a second job or side income without explaining it.
– Waiting until the last minute to gather tax forms.
How to Strengthen Your Mortgage Application
You can take simple steps to improve your chances before you apply. Start by reviewing your income and debts with a clear eye. Make sure your gross income is documented well. If you have variable pay, gather two years of records. If your debts are high, look for small balances you can pay down. Even a little progress can help your ratio.
Next, check your credit. A stronger credit profile can offset some risk in the lender’s eyes. Pay bills on time and keep credit card balances low. Avoid big purchases on credit before your loan closes. New debt can change your DTI and affect approval. It can also lower the amount you can borrow.
Finally, be honest and consistent on your application. Use the same income numbers across all forms. Explain any gaps or changes in your job history. Lenders appreciate clear communication. If you are unsure about a document or a number, ask your lender. It is better to clarify early than to fix mistakes later.
Quick Tips:
– Build a small cash reserve if you can. It shows stability.
– Keep your job steady during the application window if possible.
– Respond to lender requests fast to keep the process moving.
Common Mistakes:
– Making large credit purchases before closing.
– Changing jobs without telling your lender.
– Submitting different income numbers on different forms.
Key Takeaways
- Gross income is the main starting point: Lenders use it to measure your earning power and calculate your DTI.
- Net income still matters: It shows your real cash flow and whether your budget can handle the payment.
- DTI is a core factor: A lower ratio usually improves your approval odds and loan options.
- Variable income needs history: Overtime, bonuses, and commissions are often averaged over two years.
- Self-employed borrowers need extra paperwork: Tax returns and profit records help prove stable income.
- Good documents speed things up: Pay stubs, W-2s, tax returns, and bank statements are essential.
- Small prep steps help a lot: Lower debts, protect your credit, and keep your paperwork consistent.
Conclusion
So, do banks use gross or net income for mortgage decisions? They start with your gross income. That number helps them judge your earning power and calculate your debt-to-income ratio. But they also look at your net income, your job stability, and your debts. All of these pieces work together. When you understand the process, you can prepare with less stress. Gather your documents, keep your finances steady, and ask questions when you need clarity. With the right prep, you can move toward homeownership with more confidence.
Do banks use gross or net income for mortgage approval?
Most lenders start with your gross income because it is the clearest measure of your earning power. They also review your net income and debts to see if your monthly budget can handle the payment.
Does net income ever replace gross income in the review?
Net income is not usually the main number for approval. Lenders use it to check your real cash flow and make sure your take-home pay can cover living costs plus the mortgage.
How does the debt-to-income ratio affect my loan?
Your DTI compares your gross income to your monthly debts. A lower ratio usually improves approval odds, while a higher ratio can limit your loan amount or raise your rate.
Will overtime and bonuses count toward my income?
They can count if they are consistent. Lenders often average overtime and bonuses over two years to include them in your qualifying income.
What documents do self-employed borrowers need?
Self-employed buyers usually need two years of tax returns, business returns, and a profit and loss statement. Clean records help lenders verify stable income.
What can I do to improve my chances before applying?
Pay down small debts, protect your credit, and gather your pay stubs, tax forms, and bank statements early. Keep your job steady and avoid new credit purchases before closing.
Frequently Asked Questions
What is Do Banks Use Gross Or Net Income For Mortgage?
Do Banks Use Gross Or Net Income For Mortgage is an important topic with many practical applications.