
You do not skip a payment when your mortgage is transferred. The loan moves from one servicer to another, but your payment schedule stays the same. You still owe your regular amount on the usual due date. Always watch for transfer notices so you know where to send your money and avoid accidental late fees.
This is a comprehensive guide about Do You Skip A Payment When Your Mortgage Is Transferred.
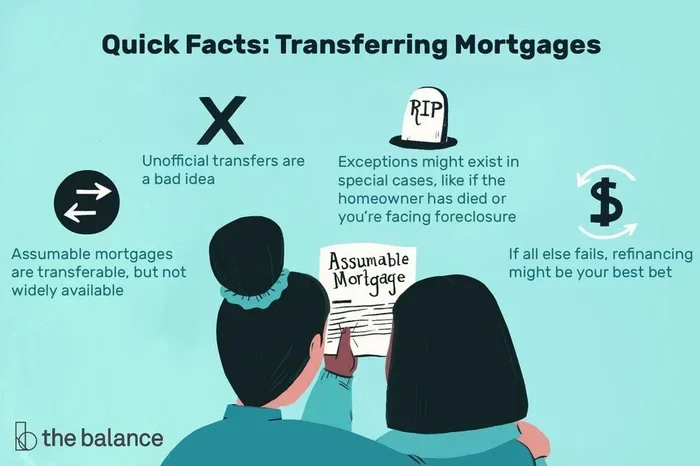
Visual guide about mortgage transfer paperwork
Image source: thebalancemoney.com
Visual guide about mortgage transfer paperwork
Image source: lawadvised.com
Visual guide about mortgage transfer paperwork
Image source: imgv2-1-f.scribdassets.com
Key Takeaways
- No payment is skipped: A mortgage transfer only changes who collects your payment, not when it is due.
- Keep paying your old lender: Continue sending payments to the original servicer until you get clear instructions to switch.
- Watch for transfer notices: Lenders must send you a notice before and after the transfer, with new payment details.
- Protect your credit: Missing a payment during the switch can hurt your score, so set reminders and confirm receipt.
- Check your first new statement: Review the new servicer account for accurate balance, interest rate, and payment date.
- Ask questions early: If anything looks wrong, call both servicers right away to fix errors before they grow.
[FEATURED_IMAGE_PLACEHOLDER]
Do you skip a payment when your mortgage is transferred? The short answer is no. A mortgage transfer does not pause your loan or erase a payment. It simply moves the servicing of your loan from one company to another. Your balance, interest rate, and due date stay the same. The only real change is where you send your monthly payment. Many people worry about this switch because it feels sudden. One day you pay one company, and the next you hear about a new one. That can be confusing. But the process is normal, and it happens often. Lenders sell loans or move them for many reasons. Even so, you still have the same home loan. You still have the same monthly obligation. The key is to stay alert, read the notices, and keep paying on time.
This article explains what really happens during a mortgage transfer. You will learn what to expect, how to protect yourself, and what steps to take so you do not miss a beat. We will also clear up common myths, like the idea that a transfer gives you a free month. It does not. Your payment clock keeps running. The good news is that you can handle this smoothly with a few simple habits. Let’s walk through the details so you feel confident, not stressed.
What Happens When Your Mortgage Is Transferred
A mortgage transfer is also called a loan servicing transfer. The loan itself does not change. The company that collects your payment does. Think of it like a change in the cashier, not a change in the price. Your original lender may sell the servicing rights to another company. That new company then handles your monthly statements, payment processing, escrow, and customer service. This can happen for many reasons. Sometimes lenders want to focus on originating new loans. Sometimes they sell pools of loans to free up capital. Sometimes a larger servicer buys the loan to manage more accounts. None of those business reasons change your personal loan terms.
Your Loan Terms Stay the Same
Your interest rate, loan balance, and payoff timeline do not change because of a transfer. If you had a fixed rate, it stays fixed. If you had an adjustable rate, it still follows its original schedule. The transfer affects servicing, not the contract. That is an important point. Many borrowers fear that a new servicer will raise the rate or alter the loan. In most cases, that cannot happen during a simple servicing transfer. The new company steps into the shoes of the old one. It must honor the same terms. If you see a change in your rate or balance, something else is going on, and you should ask questions right away.
Why Transfers Happen
Servicers often change for business reasons, not because of your personal account. Common reasons include:
- Portfolio sales: Lenders sell groups of loans to other companies.
- Servicing rights transfer: A company buys the right to collect payments and manage escrow.
- Operational changes: A lender may outsource servicing to a larger team.
- Refinancing or investor rules: Some loans move based on investor requirements.
These moves are normal in the mortgage industry. They may feel personal, but they are usually part of a bigger business strategy. Still, you deserve clear communication. You should get notices that tell you what is changing and what is not.
Do You Skip a Payment When Your Mortgage Is Transferred
Do you skip a payment when your mortgage is transferred? No. The transfer does not create a free month, a grace period, or a payment holiday. Your next payment is still due on its regular date. If your payment is due on the first of the month, it is still due on the first. The transfer may happen around that date, but the due date does not move just because the servicing rights changed hands. If you stop paying because you think the switch gives you a break, you could face late fees and credit damage. That is the risk many people do not expect.
The Truth About the “Free Month” Myth
Some borrowers hear rumors that a transfer means you can skip a month. That is not true. The idea may come from confusion about timing. Sometimes a transfer happens near the end of a billing cycle. You may get a final statement from the old servicer and a welcome letter from the new one. Those letters can make it seem like the payment schedule reset. It did not. Your loan keeps running. The only thing that changed is the address where you send money. If you want to be safe, pay on time and keep proof. That simple habit protects you from mistakes and misunderstandings.
What Actually Changes
Here is what usually changes during a transfer:
- Payment address or portal: You may need to send money to a new company or use a new website.
- Statement format: The look of your bill may change, but the numbers should match your loan.
- Customer service contact: You will call a new phone number for questions.
- Escrow handling: The new servicer may manage your taxes and insurance payments.
Here is what does not change:
- Your due date: The payment schedule stays the same.
- Your interest rate: The rate follows your original loan terms.
- Your balance: The principal and interest amounts remain consistent.
- Your obligation: You still owe the same monthly payment.
How to Handle Your Payments During the Switch
The safest approach is simple. Keep paying the old servicer until you are sure the new one is ready to receive your payment. Do not assume the switch is complete just because you got a letter. Sometimes the transfer date and the payment processing date do not line up perfectly. If you send money to the wrong place, it may take time to fix. That delay can cause stress. A little caution goes a long way. Pay the old servicer if its portal or address is still active. If you already started using the new one, make sure your payment is posted and recorded correctly.
Keep Paying the Old Servicer Until It Is Clear
If you have a payment due during the transfer window, check both servicers. Ask the old company where to send the money. Ask the new company if it has already taken over. If the old company says it still accepts payments, use that option for now. If the new company says it is ready, confirm the payment method and date. You may also want to pay a few days early during the transition. That gives you a buffer if something goes wrong. Early payment is a smart move when any account change is happening. It reduces the chance of a missed deadline.
Set Up Alerts and Double-Check Everything
Use reminders so you do not rely on memory alone. A phone alert, calendar note, or email reminder can help. Also, keep an eye on your account balance and payment history. After the transfer, compare the new statement with your records. Look for these details:
- Payment date: Make sure the due date matches your loan.
- Amount due: Check that principal, interest, taxes, and insurance add up correctly.
- Escrow account: Confirm that your tax and insurance funds are still there.
- Payment history: Verify that your recent payments show as received.
If anything looks off, contact the new servicer quickly. Small errors are easier to fix early. Waiting can make them harder to untangle.
What Notices You Should Expect
Lenders and servicers are required to send notices during a transfer. These notices help you understand the change and avoid mistakes. You should receive a notice before the transfer and another one after it. The first notice tells you the transfer is coming. It usually includes the date and the new servicer’s name. The second notice confirms the transfer happened. It gives you the new payment address, website, and phone number. These letters matter. They are your roadmap for the switch. Read them carefully. Save them in a folder so you can find them later if needed.
Before the Transfer Notice
The pre-transfer notice should tell you:
- Who is taking over: The new servicer’s name and contact details.
- When the change happens: The effective date of the transfer.
- What stays the same: Your loan terms, rate, and payment amount.
- What to do next: How to prepare for the switch and where to send payments.
If you do not get this notice, call your lender. You deserve to know what is happening with your account. A missing notice is a red flag worth checking.
After the Transfer Notice
The post-transfer notice should confirm:
- The transfer is complete: The new servicer is now handling your loan.
- New payment instructions: Where and how to pay.
- Escrow details: How taxes and insurance will be managed.
- Your rights: Information about error resolution and complaints.
Keep this notice with your mortgage documents. It can help if you need to prove that you received the correct information. It also helps if there is confusion later about where a payment should go.
Protecting Your Credit and Avoiding Mistakes
A mortgage transfer can be smooth, but only if you stay organized. The biggest risk is a missed or delayed payment. If a payment is late, your servicer may charge a fee. If it is very late, it may report the delinquency to the credit bureaus. That can hurt your credit score. You do not want that. The transfer itself does not damage your credit. A missed payment does. So the goal is simple: keep paying on time and confirm that each payment is recorded.
Common Mistakes to Avoid
Watch out for these common errors:
- Stopping payment too soon: Do not assume the old servicer is done before you get clear instructions.
- Paying the wrong place: Sending money to the wrong address can delay posting.
- Ignoring the first new statement: Always review the new account for errors.
- Forgetting escrow changes: Taxes and insurance may be handled differently now.
- Not saving proof: Keep receipts, confirmations, and notices in one place.
A little attention now can save a lot of trouble later. Mortgage transfers are routine, but your payment history is personal. Protect it.
Quick Tips for a Smooth Transition
Use these simple steps to stay on track:
- Pay early during the switch: A few extra days can prevent stress.
- Save all notices: Keep pre- and post-transfer letters in a folder.
- Test the new payment method: If the new portal is available, try a small step like viewing your balance.
- Confirm receipt: After you pay, check that the payment shows in your account.
- Ask questions fast: If something seems wrong, call right away instead of waiting.
These habits help you stay in control. You do not need to guess. You just need a clear plan and a little follow-through.
When to Call Both Servicers
Sometimes you need to talk to people. If the transfer creates confusion, do not sit on it. Call the old servicer and ask where payments should go. Then call the new servicer and confirm it is ready to receive them. If the dates do not match, ask for a clear answer. Write down the names of the people you speak with and the date of the call. That record can help if there is a dispute later. It also helps you remember what was said.
What to Ask During the Call
Good questions to ask include:
- Is my loan already with the new servicer?
- Where should I send my next payment?
- Will my payment date change?
- Is my escrow account moving with the loan?
- How can I confirm my payment was received?
Keep your tone calm and clear. Most representatives deal with these questions every day. They can usually walk you through the switch. If one person gives unclear answers, ask to speak with a supervisor or the transfer department. You deserve a straight answer about your money.
If Something Looks Wrong
If your new statement shows a different balance, a new fee, or a changed rate, do not ignore it. First, compare it with your last statement from the old servicer. Then contact the new servicer and explain the issue. If needed, contact the old servicer too. Mistakes can happen during data transfers. The sooner you catch them, the easier they are to fix. Keep notes, dates, and copies of everything. That paper trail matters if you need to escalate the problem.
Key Takeaways
Key Takeaways
- No payment is skipped: A mortgage transfer only changes the servicer, not your payment schedule.
- Keep paying on time: Continue with your regular due date to avoid late fees and credit issues.
- Follow the notices: Read the pre- and post-transfer letters carefully.
- Verify the new account: Check your first statement for accurate balance, rate, and payment details.
- Use early payments: Paying a bit early during the switch adds a safety buffer.
- Save your records: Keep notices, receipts, and call notes in one place.
- Ask early if unsure: A quick call can prevent bigger problems later.
Conclusion
So, do you skip a payment when your mortgage is transferred? No, you do not. The loan keeps moving forward, and your payment is still due on its normal date. The transfer changes the company that handles your account, not the loan itself. That means your interest rate, balance, and schedule stay the same. The safest path is to keep paying on time, read every notice, and confirm where your payment should go. A little caution during the switch can protect your budget and your credit.
If you stay organized, the process is usually simple. Save the letters, check the first new statement, and ask questions if anything looks off. Do not assume a transfer gives you extra time. It does not. Your mortgage keeps its rhythm. You just need to make sure you are sending your payment to the right place at the right time. When you do that, the transfer becomes a routine paperwork change, not a financial scare.
Frequently Asked Questions
Do you skip a payment when your mortgage is transferred?
No, you do not skip a payment. The transfer only changes the servicer, not your due date or loan terms. Keep paying on time to avoid late fees.
Can a mortgage transfer delay my payment posting?
It can if you send money to the wrong place. During the switch, confirm where to pay and keep proof of payment. Early payment can help reduce delays.
Will my interest rate change when my loan is transferred?
Usually no. A servicing transfer does not change your interest rate or loan balance. If your rate looks different, ask the servicer to explain why.
What should I do if I get a transfer notice near my due date?
Check both servicers and ask where to send the payment. If the old servicer still accepts payments, use that option until the new one confirms it is ready.
Is it safe to pay the new servicer right away?
It can be, if the new servicer has confirmed it is ready to receive payments. If you are unsure, continue paying the old servicer until the transfer is clearly complete.
What if my first new statement looks wrong?
Compare it with your last old statement and contact the new servicer quickly. Save your notices and receipts so you can explain the issue clearly.