Finding the best online mortgage pre approval process can save you time and stress during your home search. We break down exactly how digital lenders work, what documents you need, and how to compare rates without leaving your couch. You will learn which platforms offer the fastest decisions and the most transparent pricing. This guide helps you move from browsing listings to making confident offers with a solid financial foundation.
Buying a home feels exciting until you realize financing can slow everything down. That is why smart buyers start with the best online mortgage pre approval process before they even tour a property. Digital lenders have changed the game by letting you apply, upload documents, and get a decision from your phone or laptop. You do not need to sit in a branch for hours anymore. You just need a clear plan and the right platform.
This guide walks you through how online pre approval works, what to expect, and how to choose a lender that fits your situation. We will cover credit checks, rate shopping, document prep, and common pitfalls so you can move forward with confidence. If you want a faster, simpler path to a verified budget, you are in the right place.
Key Takeaways
- Speed matters: Online pre approval can often deliver decisions in minutes or hours, not days.
- Compare multiple lenders: Rates and fees vary widely, so shopping around protects your budget.
- Know your credit profile: Soft pulls help you explore options without hurting your score.
- Read the fine print: Some online quotes are estimates, not locked commitments.
- Prepare your documents: Pay stubs, tax returns, and bank statements speed up verification.
- Understand loan types: Conventional, FHA, and VA loans each have different online eligibility rules.
- Use pre approval strategically: Sellers take your offer more seriously when you have verified financing.
📑 Table of Contents
- What Makes the Best Online Mortgage Pre Approval Process Stand Out
- How Online Pre Approval Works Step by Step
- Choosing the Right Online Lender for Your Situation
- Documents and Details That Help You Get Pre Approved Faster
- Understanding the Difference Between Pre Qualification and Pre Approval
- Common Mistakes to Avoid With Online Mortgage Pre Approval
- Expert Tips for a Smoother Online Pre Approval Experience
- Final Thoughts on Finding the Best Online Mortgage Pre Approval
What Makes the Best Online Mortgage Pre Approval Process Stand Out
Not all online pre approvals are created equal. Some platforms give you a quick estimate, while others verify your finances and issue a stronger conditional commitment. The best online mortgage pre approval experience usually includes a smooth application, clear communication, and a lender that actually reviews your income, debts, and assets.
A strong digital process should feel transparent. You should know what information is needed, how long the review takes, and whether your quote is an estimate or a more solid pre approval. If a site promises instant results but skips key verification steps, that may not help you when a seller requests proof of financing.
Fast Application Without Sacrificing Accuracy
The best platforms ask the right questions without making the form feel endless. You should be able to enter your employment details, monthly debts, down payment amount, and desired loan type in a clean interface. Good design matters because a confusing form can lead to mistakes that delay your review.
Speed is helpful, but accuracy matters more. A rushed application that misses a debt payment or enters the wrong income figure can create problems later. The ideal online process balances quick entry with smart prompts that help you avoid errors.
Clear Communication and Status Updates
You should not have to guess what happens after you submit your application. Top online lenders send confirmation messages, explain the next steps, and let you track your progress. If they need more documents, they should tell you exactly what is missing and why it matters.
This kind of communication builds trust. It also helps you stay organized during a busy home search. When you know what is happening, you can respond faster and keep your offer moving.
How Online Pre Approval Works Step by Step
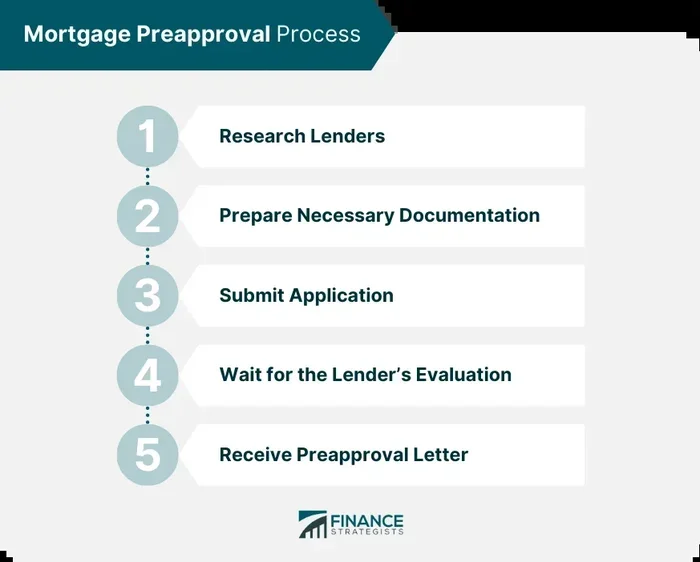
Understanding the flow helps you prepare and avoid delays. Most online pre approvals follow a similar path, even if the interface looks different from one lender to another. The process usually starts with a short form, followed by a credit review and document verification.
Once you submit your information, the lender evaluates your financial profile and determines whether you meet their guidelines. If everything lines up, you may receive a pre approval letter or a conditional approval that outlines the loan amount and next steps. If something needs clarification, the lender may ask for additional paperwork.
Step One: Start With a Short Application
Your first step is usually a brief online form. You will enter basic details such as your name, contact information, employment status, income, monthly debts, and desired loan amount. Some platforms also ask about your down payment, property type, and whether you are buying a primary home or an investment property.
Keep your answers consistent with the documents you plan to upload later. Discrepancies can slow down the review. For example, if you list a certain salary but your pay stubs show something different, the lender may need to reconcile the numbers.
Step Two: Credit Check and Rate Snapshot
After the application, many lenders perform a credit check. Some use a soft inquiry first to give you an initial view of your options. Others may move to a hard inquiry when you choose to proceed with a full pre approval. It is important to understand which type of check you are authorizing.
A credit check helps the lender estimate your rate and eligibility. Your credit score, payment history, and debt levels all influence the outcome. If your credit profile is strong, you may see more favorable terms. If there are issues, the lender may still work with you but could adjust the loan amount or rate.
Step Three: Document Upload and Verification
This is where online pre approval becomes more serious. You may be asked to upload pay stubs, W-2s, tax returns, bank statements, and identification. Some lenders also request proof of assets or explanations for large deposits. Uploading clear, recent documents can speed up the review.
Think of this stage as the proof phase. The lender wants to confirm that the numbers in your application match your actual financial records. If you are self-employed, you may need additional paperwork such as profit-and-loss statements or business tax returns.
Step Four: Review and Pre Approval Letter
Once the lender finishes the review, you may receive a pre approval letter or a conditional commitment. This document often states the loan amount you qualify for, the loan type, and any conditions that must be met before closing. Some online lenders let you download or email the letter directly from their portal.
A pre approval letter can be useful when you make an offer. It shows sellers that a lender has reviewed your finances and that you are serious about the purchase. Just remember that pre approval is not the same as final loan approval, which comes after the property appraisal and underwriting.
Choosing the Right Online Lender for Your Situation
The best online mortgage pre approval choice depends on your goals, credit profile, and how much guidance you want. Some borrowers prefer a fully digital experience with minimal phone calls. Others want a hybrid model where they can message a loan officer when questions come up. Both approaches can work well if the lender is reputable and clear.
Start by comparing a few key factors. Look at how long the application takes, what documents are required, whether the quote includes estimated closing costs, and how quickly you receive a decision. Also check whether the lender offers the loan types you need, such as conventional, FHA, or VA loans.
Compare Rates, Fees, and Loan Options
Interest rates get the most attention, but fees matter too. An online quote should give you a realistic picture of the total cost, not just the monthly payment. Ask yourself whether the estimate includes origination charges, appraisal fees, title costs, and other common expenses.
Loan options also matter. If you have a smaller down payment, an FHA loan may be a better fit. If you are a veteran, a VA loan could offer strong benefits. If you want a traditional financing path, a conventional loan may be ideal. The best online pre approval platform should help you explore the options that match your profile.
Look for Transparency and Responsiveness
A trustworthy lender explains what you are getting and what still needs to be confirmed. They should be clear about whether the pre approval is conditional and what conditions remain. They should also respond promptly if you have questions about your quote or documents.
Responsiveness can make a big difference when you are under a deadline. If you are preparing an offer, you do not want to wait days for a simple clarification. Good customer support is a hidden but valuable part of the online mortgage experience.
Documents and Details That Help You Get Pre Approved Faster
Preparation is one of the easiest ways to improve your online pre approval experience. When your documents are ready and your information is consistent, the review tends to move more smoothly. You do not need perfect paperwork, but you do need organized paperwork.
Before you start, gather the basics. Having these items handy can reduce back-and-forth messages and help you avoid unnecessary delays.
- Recent pay stubs: Usually the last 30 days, depending on the lender.
- W-2s or tax forms: Often the last one to two years.
- Tax returns: Especially helpful if you are self-employed.
- Bank statements: Recent statements for checking, savings, and other accounts.
- ID and Social Security details: For verification purposes.
- Debt information: Details on auto loans, student loans, credit cards, and other obligations.
- Down payment sources: Records that show where your funds are coming from.
Keep Your Financial Profile Steady During the Process
Once you begin the pre approval process, it helps to keep your finances stable. Big new purchases, new credit lines, or large unexplained deposits can raise questions. Lenders want to see a clear picture of your ability to repay the loan, so sudden changes can complicate the review.
This does not mean you cannot manage your money. It simply means you should avoid unnecessary financial moves while your application is active. If you are unsure whether a change matters, ask your lender before making it.
Watch for Common Document Mistakes
Small errors can slow things down. Blurry uploads, outdated statements, and missing pages are common issues. Another frequent problem is inconsistent names or addresses across documents. If your forms do not match, the lender may need extra time to verify your identity and records.
A quick review before uploading can save time. Make sure the documents are legible, current, and complete. If a statement spans multiple pages, send all relevant pages so the lender can see the full picture.
Understanding the Difference Between Pre Qualification and Pre Approval
People often use these terms loosely, but they can mean different things. Pre qualification is usually a quicker, less detailed estimate based on the information you provide. Pre approval typically involves more verification and may carry more weight when you make an offer. The best online mortgage pre approval process should be clear about which stage you are in.
If you are only exploring your budget, pre qualification may be enough to start. If you are ready to make offers, a more verified pre approval can be more useful. Knowing the difference helps you set the right expectations and choose the right time to move forward.
When a Stronger Pre Approval Helps Most
A more thorough pre approval can be especially helpful in competitive markets. When sellers see that a buyer has already cleared several financing steps, they may view the offer as more reliable. This can matter if you are bidding on a home with multiple interested buyers.
That said, a stronger pre approval still depends on the lender’s process. If the lender only did a surface-level review, the letter may not be as persuasive. Look for a process that actually verifies income, assets, and credit before you rely on it for an offer.
Questions to Ask Before You Rely on a Letter
Before you use a pre approval letter, ask a few practical questions. How long is it valid? What conditions are attached? Does the lender expect any additional verification before closing? Is the quoted amount still accurate if rates change? These questions help you understand how much confidence you can place in the letter.
It is also smart to ask how the lender handles communication during the next steps. If you plan to move quickly, you want a lender who can keep pace with your timeline and answer questions without unnecessary delays.
Common Mistakes to Avoid With Online Mortgage Pre Approval
Online convenience can make the process feel simple, but that does not mean you should rush through it carelessly. A few common mistakes can weaken your position or create confusion later. Avoiding them can make your home search smoother and more effective.
One mistake is treating every online quote as a final commitment. Another is submitting inconsistent information. A third is ignoring closing costs and focusing only on the loan amount. These issues can lead to surprises when you are ready to buy.
Mistake One: Assuming Every Quote Is the Same
Different lenders may give you different estimates based on the same basic information. That is because they may use different guidelines, rate assumptions, and fee structures. If you only look at one quote, you may miss a better option.
Comparing a few offers gives you a better sense of your real range. It also helps you spot outliers. If one quote looks unusually low or unusually high, ask questions before you decide.
Mistake Two: Overlooking Credit and Debt Details
Your credit profile and monthly debts influence what you can borrow. If you skip a careful look at your own finances, you may be surprised by the result. A lender can only work with the information available, so hidden debts or credit issues can affect the outcome.
Reviewing your credit report and monthly obligations ahead of time can help you explain any concerns. It also gives you a chance to correct errors or pay down balances if that makes sense for your situation.
Mistake Three: Waiting Too Long to Get Started
Some buyers wait until they find the perfect home before thinking about financing. That can create pressure if the market moves quickly. Starting the pre approval process earlier gives you a clearer budget and more flexibility when you see a home you like.
You do not have to lock in a loan months in advance, but having a verified budget can help you shop smarter. It also reduces stress because you know what you can afford before you fall in love with a property.
Expert Tips for a Smoother Online Pre Approval Experience
A few simple habits can make the online process much easier. The goal is not to overcomplicate things. The goal is to stay organized, ask clear questions, and move step by step. If you do that, you can often save time and reduce frustration.
Here are a few practical tips that can help:
- Start with a realistic budget: Include monthly payment comfort, not just the maximum loan amount.
- Use a checklist: Track your documents, application status, and follow-up tasks.
- Ask about rate locks: Understand when a rate can be locked and what that means for you.
- Keep copies of everything: Save your submitted forms and uploaded documents in one place.
- Respond quickly to requests: Fast replies often keep the process moving.
- Read the estimate carefully: Look for the interest rate, estimated monthly payment, and key fees.
When to Get Personal Help
Even the best online tools sometimes need a human touch. If your income is complex, you own a business, or you have unusual assets, a conversation with a loan officer can help clarify your options. Online pre approval can still be the starting point, but a little guidance may prevent confusion.
Personal help can also be useful if you receive a conditional approval with requirements that are hard to understand. A clear explanation can help you decide what to provide next and how long it may take.
Final Thoughts on Finding the Best Online Mortgage Pre Approval
The best online mortgage pre approval experience is the one that gives you clarity, speed, and enough verification to help you shop with confidence. A good digital process should be easy to use, honest about what is included, and ready to support you when questions come up. If you prepare your documents, compare a few lenders, and understand the difference between an estimate and a stronger pre approval, you can move through the early stages of home buying with less stress.
Take your time to choose a platform that fits your needs. Look for transparency, responsiveness, and loan options that match your situation. Then use your pre approval as a practical tool, not just a piece of paper. With the right approach, you can walk into your next home search knowing your budget, your next steps, and your financing path.
Frequently Asked Questions
What is the best online mortgage pre approval for a first-time home buyer?
The best option is usually a lender that offers a simple application, clear document requests, and loan choices suited to first-time buyers. Look for a platform that explains costs honestly and gives you a realistic budget range. If you are new to the process, a lender with strong support can make a big difference.
How long does online mortgage pre approval usually take?
It can take anywhere from a few minutes to a few business days, depending on the lender and how quickly you submit documents. A basic quote may come quickly, while a more verified pre approval often takes longer. The timeline also depends on how complex your finances are.
Does applying online hurt my credit score?
Not always. Some lenders start with a soft inquiry that does not affect your score, while others may use a hard inquiry when you move forward with a full application. It is important to read what type of credit check the lender performs before you submit.
What documents do I need for the best online mortgage pre approval?
You will usually need recent pay stubs, tax forms, bank statements, identification, and details about your debts and down payment. Self-employed borrowers may need extra paperwork such as tax returns or business records. Having these documents ready can speed up the review.
Is an online pre approval letter enough to make an offer?
It can be, but the strength of the letter depends on how thoroughly the lender verified your finances. A more complete pre approval is usually more useful to sellers than a quick estimate. Always check what conditions are attached before you use it for an offer.
Can I compare multiple online pre approvals without lowering my chances?
Yes, if you do it within a reasonable shopping window and understand how each lender checks your credit. Many buyers compare a few options to find better rates and terms. Just be careful not to submit too many full applications in a short period without knowing how the lender reports the inquiry.